Corn • Soybeans • Wheat
Justin N
Harvest pressure continues to be a major feature across the grain markets, but futures remain well above their late-summer lows. Traders are balancing large U.S. supplies against strong export demand, South American weather risks, and ongoing uncertainty surrounding Black Sea grain flows.
CORN
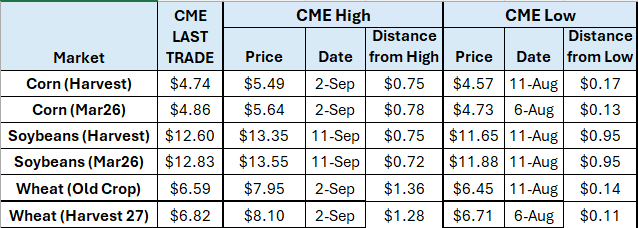
December Corn futures settled below $4.75/bu, following a hard selloff after USDA increased both production and ending stock estimates. Overall price action for the week saw corn lose $0.06/bu. USDA now estimates the 2026 crop at 16.034 billion bushels, with ending stocks projected at 1.849 billion bushels. Locally not much progress is being made with corn, although in some areas there has been opportunity to get early planted acres out.
Market Outlook
Corn remains caught between harvest pressure and improving demand. Export sales and ethanol usage have been supportive, but large supplies continue to outweigh demand improvements. The market will need either stronger exports or weather concerns in South America to generate a significant recovery.
SOYBEANS
November Soybean futures recently closed near $12.60/bu. being pressured down by the grain belts harvest progress ramping up, and an estimated record crop based on the latest WASDE. Overall price action for the week saw soybeans lose $0.26/bu Soybean prices have held together better than corn due to ongoing export interest and South American weather uncertainty. Locally harvest was able to make some good early strides across WNY before mother nature dropped some precipitation later in the week.
Market Outlook
Traders are beginning to focus on Brazilian planting progress and early-season weather. Any production issues in South America could quickly tighten the global balance sheet and support prices.
WHEAT
December CBOT Soft Red Winter Wheat futures recently settled near $6.70/bu. Wheat has pulled back from September highs as global supplies remain adequate and corn weakness spills into the wheat market. Overall price action for the week saw wheat lose $0.10/bu. USDA increased U.S. ending stocks after lowering export projections.
Market Outlook
Global weather, Black Sea exports, and world demand remain the primary drivers. Wheat still holds a premium to last winter's values but has struggled to maintain the rally seen earlier this fall.
Key Things We're Watching
✅ South American planting progress and weather
✅ U.S. export demand, especially corn and soybeans
✅ Fund positioning following the USDA report
✅ Harvest pace and final yield results
Bottom Line
Corn remains under pressure from burdensome supplies and is trading almost exactly midway between its recent high and low. Soybeans continue to be the leader of the grain complex, despite facing significant harvest pressure. Wheat has cooled from its September rally but remains well above seasonal lows. As harvest continues, market direction will increasingly depend on export demand and South American weather developments.
Contact our grain team to discuss cash bids, basis opportunities, contracting alternatives, and post-harvest marketing strategies.
Futures and basis are subject to change. This update is for informational purposes only and is not a recommendation to buy or sell futures or cash grain.
